Oil futures settled higher on Friday, November 20, 2026, but the gains were insufficient to prevent a third consecutive weekly loss as oversupply concerns dominated market sentiment throughout the week. Brent crude for January delivery added 59 cents, or 0.64%, to settle at $92.57 per barrel on the London ICE Futures Exchange . US West Texas Intermediate for December delivery rose 77 cents, or 0.93%, to close at $83.98 per barrel . For the week, Brent headed toward a decline of nearly 4%, while WTI fell approximately 5% .
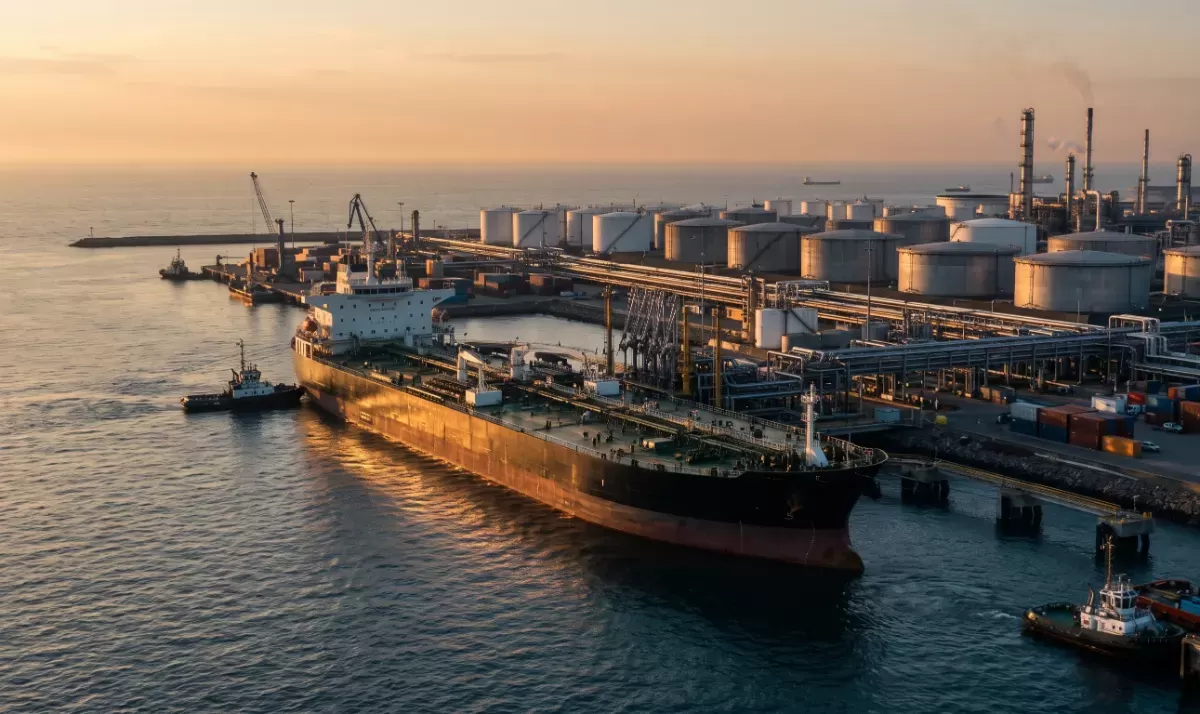
The primary driver of the weekly decline was the recovery of oil flows through the Strait of Hormuz. Shipping activity through the critical chokepoint has returned close to pre-conflict levels, reinforcing expectations that global supply will outpace demand in the coming months . The International Energy Agency forecast that the global market will return to surplus in the fourth quarter of 2026, with supply averaging 105 million barrels per day—about 1.7 million barrels per day above demand . The IEA also noted that 71 million barrels remaining from a record strategic reserve release in March 2026, including 15 million barrels of diesel, will continue flowing into the market through late February 2027 .
Additional supply-side pressure came from major producers. Saudi Arabia's crude exports rose nearly 21% in September 2026 to 5.38 million barrels per day, the highest level since February, according to data from the Joint Organisations Data Initiative . US commercial crude inventories surged by 3.4 million barrels to 417.8 million barrels in the week ending November 13, far exceeding analyst expectations of a modest 58,000-barrel increase, according to Energy Information Administration data released November 18 . The inventory build intensified selling pressure midweek.
Goldman Sachs revised its forecast downward, projecting Brent to average just $88 per barrel in 2027 and to decline toward $78 per barrel by December 2027. The bank cited efforts by Middle Eastern producers to expand ship-to-ship transfers and pipeline capacity to reduce dependence on the Strait of Hormuz as factors that would structurally lower geopolitical risk premiums . These forecasts reinforced the bearish narrative that supply security concerns are gradually diminishing, at least in the medium term.
Friday's rebound was attributed to short-covering ahead of the US Thanksgiving holiday and renewed anxiety over potential US-Israeli military action against Iran. John Kilduff, partner at Again Capital, noted that traders believe US military forces remain at high readiness, allowing conflict fears to dominate market psychology more than pre-holiday buying . Additionally, Houthi forces demanded the immediate evacuation of civilians and workers near Saudi Red Sea ports and warned of attacks if the Saudi-led coalition strikes Yemen's Hodeidah port . These developments provided a temporary floor but could not offset the week's broader selling pressure.
The weekly decline extended a broader correction from October peaks. Brent had surged to $124 per barrel in October, the highest since July 2022, as attacks on tankers in the Middle East and Black Sea disrupted flows and reduced available tanker capacity . Prices have since retreated as supply workarounds—including pipeline bypass routes, ship-to-ship transfers along Oman's coast, and the restart of Saudi Arabia's East-West Pipeline—have gradually restored market access . The EIA forecast Brent to average around $100 per barrel in November and December before declining below $90 in the second quarter of 2027 as inventories build .
For shipping markets, the price trajectory carries mixed implications. Lower crude prices reduce the value of cargo carried, potentially softening tanker freight rates that had spiked during the October supply disruption. However, the return of Hormuz transits to near-normal levels signals improved operational conditions for tanker operators who have faced elevated war risk premiums and route disruptions. The IEA noted that record freight costs had hit Asian refiners in October, though margins have since weakened as supply conditions normalize . The coming weeks will test whether the oversupply narrative holds against the persistent geopolitical risks that have repeatedly disrupted expectations throughout 2026.